
Money
How To Compare Physical Assets Before Adding Them To A Portfolio

Key Takeaways
- Physical assets can broaden a portfolio, but they still carry market, ownership, and selling risks.
- The best comparison starts with purpose, liquidity, costs, cash flow, and the knowledge needed to own the asset well.
- Real estate, metals, farmland, collectibles, and vehicles have very different ownership demands.
- Personal enjoyment can be a valid reason to buy a tangible asset, but it should not be confused with dependable investment performance.
- A purchase limit, a holding plan, and an exit plan can reduce emotional decision-making.
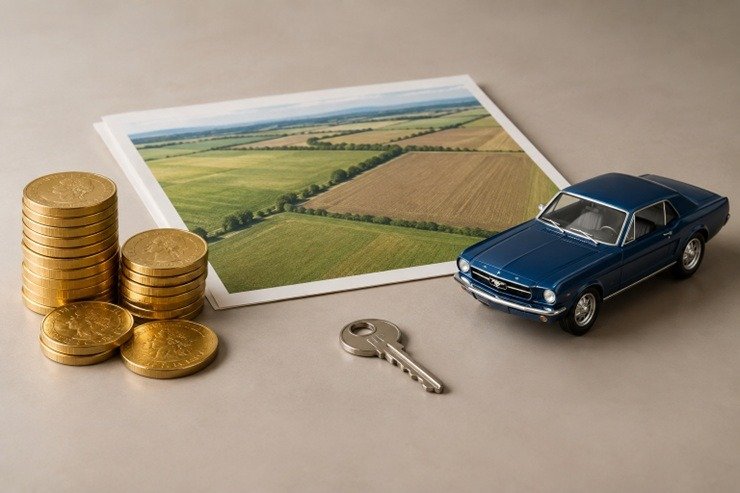
Physical assets are tangible items with a real-world presence, such as property, bullion, land, art, equipment, or collector vehicles. Before making a purchase, investors should understand how direct ownership differs from owning shares in a fund or in a company in the same category. A practical overview of investing in physical assets at Preserve Gold can help clarify the questions that come with direct ownership, including storage, insurance, and resale planning. Adding a physical asset to a 2026 portfolio is not simply a matter of choosing what seems most valuable today. The better question is whether the asset has a clear role in a broader financial plan. A rental property may produce income, whereas a gold coin or painting generally depends on future resale value rather than regular cash flow.
What Counts as a Physical Asset?
Physical assets are often called tangible, hard, or real assets because they can be owned, used, stored, repaired, or inspected. Common examples include residential and commercial real estate, gold and silver, farmland, timberland, fine art, antiques, classic cars, machinery, and natural-resource interests. Their values can be influenced by local conditions, scarcity, condition, supply and demand, operating income, and buyer interest.
Direct ownership gives the buyer control over the item itself, but it also creates practical responsibilities. A real estate fund, for instance, can offer exposure to property without requiring the investor to find tenants or arrange repairs. Directly owning a building means taking on those tasks, either personally or through paid management.
Why Investors Consider Physical Assets
Investors often look at physical assets when they want holdings that may respond differently to stock and bond markets. Rents, crop yields, construction costs, commodity demand, and collector preferences can affect tangible assets in ways that do not perfectly mirror public securities. That difference does not guarantee protection from losses, nor does it mean every physical asset improves diversification. A portfolio should still be judged as a whole. The Securities and Exchange Commission explains that spreading money among different investments can help reduce risk, although diversification cannot prevent every loss. A large purchase of a single property, metal, or collectible can create concentration risk even when the rest of the portfolio appears varied.
The Five-Part Test for Comparing Physical Assets
1. Purpose
Start by naming the job the asset is expected to do. Possible goals include long-term growth, income, inflation sensitivity, diversification, wealth storage, or personal use. One asset rarely excels at all of them. A vacation home may offer enjoyment and potential rental income, but it may not be easy to sell quickly or operate at a profit.
2. Liquidity
Liquidity is the ability to sell an asset promptly at a reasonable price. Widely traded bullion may have more active resale channels than a rare automobile or regional commercial property. Art, land, and specialty collectibles can require appraisals, auctions, marketing, inspections, or patient negotiation. Ask who the likely buyer is and what would happen if a sale were needed within weeks rather than years.
3. Costs
Look beyond the purchase price. Physical ownership can involve storage, security, insurance, repairs, maintenance, property taxes, transportation, financing interest, dealer spreads, commissions, appraisals, and management fees. These costs can reduce the result from an otherwise successful sale. Build an annual ownership estimate and include a reserve for unexpected repairs or vacancies.
4. Income and Cash Flow
Some physical assets can produce income through rent, leases, farming arrangements, or equipment use. Others, including most bullion, art, and collectibles, do not generate regular cash flow. For a non-income asset, consider how ongoing expenses will be covered while waiting for an appropriate time to sell. Avoid assuming that appreciation will cover all ownership costs.
5. Risk and Knowledge
Every category has distinct risks. Property can face vacancy, damage, local regulation, and financing pressure. Metals can fluctuate in price and require secure custody. Collectibles can be affected by condition, authenticity, changing tastes, and limited buyer pools. Before buying, verify the title or ownership records, inspect the condition, review provenance where relevant, and assess the seller’s reputation.
Comparing Common Physical Asset Categories
Real Estate
Real estate may offer use value and possible rental income, but it often requires substantial capital and attention. Review location, tenant demand, insurance availability, property taxes, local rules, maintenance history, and the cost of professional management. Financing can magnify gains and losses, so repayment obligations should remain manageable if income falls.
Precious Metals and Commodities
Gold, silver, platinum, and similar holdings can be compact and recognizable, but form matters. Coins, bars, purity, dealer pricing, storage arrangements, and resale spreads can affect the outcome. Physical metals generally do not provide income, so they should be evaluated as a holding that may need secure storage rather than as a cash-producing asset.
Farmland and Timberland
Land tied to agriculture or timber can offer exposure to productive acreage and lease arrangements. It also requires knowledge of soil, water, access, weather, management, environmental obligations, and local markets. For buyers without regional expertise or a trusted operator, these assets may be harder to evaluate and manage than they first appear.
Art, Collectibles, and Specialty Vehicles
These assets can provide enjoyment, scarcity, and cultural value, but rarity alone does not create liquidity. Authentication, condition reports, climate-controlled storage, insurance, restoration, and buyer demand all matter. A classic vehicle may attract enthusiasts, yet maintenance and restoration costs can be high. Buy only when the personal value remains worthwhile even if the financial return is modest or delayed.
How Physical Assets Fit Into a Broader Portfolio
- List current holdings, debts, cash needs, and insurance coverage before setting a purchase amount.
- Decide how much of the portfolio can reasonably be tied up in assets that may be slow to sell.
- Compare the proposed asset with existing exposure, rather than judging it on its own recent performance.
- Keep emergency savings separate from money intended for a long-term physical holding.
- Review the position periodically according to a written plan, not daily headlines or auction excitement.
Questions to Ask Before Buying
- What makes this asset valuable today, and what could reduce that value?
- Who is likely to buy it later, and how broad is that buyer pool?
- What costs continue after the purchase?
- Can value, condition, title, and authenticity be independently verified?
- Would the purchase still make sense if its price stayed flat for several years?
- What taxes could apply when the asset is sold?
Common Mistakes to Avoid
Common errors include buying solely because prices have recently risen, overlooking selling costs, using excessive borrowed funds, skipping inspections or authentication, and putting too much capital into a single item. Tax treatment also deserves attention. The IRS identifies art, coins, and certain metals as collectibles for federal tax purposes, so buyers should review the rules on capital gains and losses and seek qualified tax advice for their circumstances.
Conclusion
Physical assets can add useful variety to a portfolio when their practical demands align with the owner’s goals, budget, and knowledge. However, owning something tangible does not automatically make it a suitable investment. Each asset may involve different purchase costs, maintenance needs, storage requirements, insurance expenses, and resale conditions that can affect its overall value. A disciplined comparison of liquidity, costs, income potential, valuation, and risk can reveal whether an asset belongs in the plan or is better treated as a personal purchase. Owners should also consider how easily they could sell the asset if their financial needs change, since some holdings may take time to value or find a buyer. The strongest approach usually preserves flexibility, maintains adequate cash, and avoids relying on any single tangible holding to carry the entire portfolio. By considering both the potential benefits and ongoing responsibilities, investors can make choices that better support their broader financial priorities.








How To Compare Physical Assets Before Adding Them To A Portfolio

How Do the Brain and Body Work Together?

How Digital Convenience Is Changing the Way We Discover and Buy What We Love

Nano Banana 2.5 and the Rise of Prompt-Led Image Creation

These 5 Shower Filter Brands Will Improve Your Water Quality and Your Wellbeing

Your Dental Checkup Is Doing More For Your Health Than You Think

How to Plan a Home Renovation Materials List and Timeline

The New Limousine: How Luxury Mercedes Sprinter Vans Are Changing the Ride

Cloud Migration Mistakes Businesses Still Make and How to Avoid Them

Small Daily Choices For A Healthier, Lower-Waste Oral Care Routine

100 Motivational Quotes to Inspire You in 2026

How to Create a Vision Board That Actually Works (2026)

22 Best Self-Help Books to Read in 2026

How to Achieve Personal Growth in 2026

New Year Wishes and Quotes to Inspire and Celebrate (2026)

Loeb Smith reviews: Why Crypto Licensing Demands Patience, Structure, and Skepticism

How to Leverage Personal Development for Career Advancement

Top Fitness Coach Certification Programs for Aspiring Trainers

From Denver to Vail: Secrets, Snow, and Soul of the Rockies

How to Choose the Best Manali Tour Package for a Family-Friendly Vacation?
-
 Motivation6 years ago
4 Fun New Hobbies To Try This Year
-

 Quotes4 years ago
53 Motivational Gym Quotes to Fuel Gym Workout
-
 Quotes11 years ago
50 Most Powerful Quotes Ever Spoken
-

 Travel2 years ago
Why You Should Travel More: The Many Benefits of Seeing the World
-
 Quotes9 months ago
100 Motivational Quotes to Inspire You in 2026
-

 Quotes3 years ago
43 Inspirational Quotes About Thoughts
-

 Quotes4 years ago
Motivational Quotes by Famous People
-
 Quotes1 year ago
100 Motivational Quotes to Start Your Day with Positivity