
Money
Mortgage Fraud Red Flags Homebuyers Should Check Before Closing

Key Takeaways
- Fraud can appear in loan applications, property information, final documents, and payment instructions.
- A sudden change to wire instructions should always be verified independently.
- Borrowers should review every material detail before signing, including names, rates, fees, and cash due at closing.
- Pressure, secrecy, and rushed decisions are warning signs, not reasons to skip verification.
- If money is sent to the wrong account, contacting the bank immediately may improve the chance of stopping or recovering the transfer.
Why Homebuyers Need a Fraud Check Before Closing
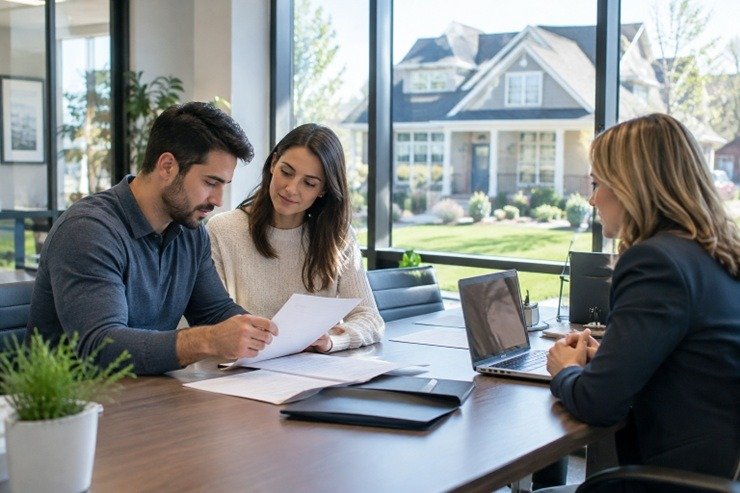
Buying a home requires buyers to share financial records, sign detailed agreements, and move substantial funds within a limited timeline. Those conditions can create opportunities for mortgage fraud, especially when someone relies on the buyer feeling rushed, overwhelmed, or reluctant to question a professional.
Fraud is not limited to one stage of a transaction. It can involve false information on a mortgage application, altered property details, misleading appraisal information, or a convincing message that redirects closing funds. A careful review before closing helps buyers catch inconsistencies while there is still time to address them.
For example, a buyer may receive an email that appears to come from a settlement office on the morning of closing. The message says wiring instructions have changed and warns that a delay will put the purchase at risk. Even if the email includes familiar names or logos, the buyer should not send money until the change is confirmed through a trusted phone number.
Red Flags in Mortgage Applications
A mortgage application should accurately reflect the borrower’s income, assets, debts, employment, and intended use of the property. If a form is confusing, ask the lender or loan officer to explain it before signing. Never assume an inaccurate entry is harmless because someone else completed the paperwork.
- Someone suggests overstating income, savings, employment history, or the amount of money available for closing.
- You are told not to disclose debts, other properties, or financial obligations.
- You are encouraged to state that the home will be your primary residence when you actually plan to rent it out or use it as an investment.
- Names, addresses, dates, account balances, or signatures do not match the information you provided.
- You are asked to sign blank pages, incomplete forms, or documents you have not had time to read.
Errors should be corrected before signing. A borrower remains responsible for the accuracy of statements made in connection with a loan, even when a lender, broker, agent, or other party prepared the documents.
Red Flags in Property and Appraisal Details
Property records and valuations deserve the same attention as loan paperwork. An appraisal that seems far above comparable nearby sales, vague repair descriptions, missing contract pages, or unexplained amendments may warrant questions. Buyers should ask for complete copies of documents and clear explanations of changes.
It is also reasonable to understand whether important parties have undisclosed relationships. A rapid resale at a substantially higher price is not automatically improper, since legitimate renovations can add value. However, a transaction becomes more concerning when the value, condition, ownership history, or terms appear to be misrepresented.
Closing Payment Scams to Watch For
Closing payment scams often depend on impersonation. The warning signs of mortgage closing scams include unexpected messages that change wiring details or demand immediate action. Criminals may imitate a real estate professional, lender, attorney, title company, or escrow officer to make a request seem legitimate.
- New wire instructions arrive shortly before closing.
- A message claims the transaction will fail unless money is sent immediately.
- An email address differs from a known address by one letter, an extra character, or an unusual domain.
- You are asked to transfer funds to an unfamiliar account without speaking directly with a trusted contact.
- The payment amount or recipient conflicts with your Closing Disclosure or earlier written instructions.
How to Verify Closing Instructions Safely
- Stop before initiating any wire or electronic transfer.
- Call the lender, attorney, escrow officer, or settlement agent using a phone number saved earlier in the transaction or found through a trusted official channel.
- Ask the person to confirm the recipient account name, routing details, payment amount, and reason for any change.
- Compare the information with prior instructions and your final closing documents.
- Do not rely on a phone number, link, or reply address contained in the unexpected message.
- Record who confirmed the details, when they did so, and what information they provided.
Document Checks to Complete Before Signing
Review the final Closing Disclosure alongside the earlier Loan Estimate. Focus on the interest rate, loan amount, projected payment, closing costs, lender credits, deposit credits, payoff amounts, and cash needed to close. Ask about any material number that changed or that you do not understand.
- Confirm every borrower’s legal name and the property address.
- Verify the loan type, term, interest rate, and monthly principal and interest payment.
- Review fees, credits, taxes, insurance amounts, and prepaid items.
- Confirm ownership details and any conditions that must be satisfied before closing.
- Request corrected documents and adequate review time instead of signing under pressure.
How Technology Has Changed Fraud Risks
More realistic fake emails, altered documents, cloned websites, and voice impersonation attempts can make a scam harder to recognize at a glance. A familiar name, caller ID, logo, or voice should not be treated as proof of identity. Independent verification through a separate channel remains the safest response to unexpected requests involving money or sensitive data.
Use secure portals when provided by trusted parties, create strong and unique passwords, and enable multi-factor authentication for email and financial accounts. Never share passwords, one-time security codes, or account credentials because of an unsolicited call, email, or text.
What to Do If Something Feels Wrong
- Pause the transaction if the concern involves funds, identification, or a document you cannot verify.
- Tell the lender and closing professionals that you are independently confirming the request.
- Save emails, texts, documents, phone numbers, and screenshots of payment instructions.
- Request a fresh copy of the disputed document directly from a known contact.
- Contact your bank immediately if funds have already been sent to an incorrect account.
- Report suspected impersonation or fraud through the Federal Trade Commission’s fraud reporting process and follow any instructions from your bank or law enforcement agency.
Questions Homebuyers Should Ask Before Closing
- Who is authorized to change payment instructions?
- How will wire details be confirmed before funds are sent?
- Which fees or credits changed after the initial estimate, and why?
- Who should I contact if an email or call appears suspicious?
- Which documents should I review before the closing appointment?
- What is the immediate procedure if a wire transfer is sent to the wrong account?
Final Checklist for a Safer Closing
- Review all final documents carefully.
- Confirm the exact amount needed to close.
- Verify payment instructions by phone using trusted contact details.
- Question sudden changes to fees, documents, account information, or deadlines.
- Keep records of confirmations and corrections.
- Never let urgency replace verification.
Conclusion
A fraud check does not have to derail a home purchase. It is a practical step that protects buyers from errors, impersonation, and costly payment scams. When a document, valuation, message, or payment request seems different from what you expected, pause and verify it independently. A few careful minutes before closing can help protect savings that took years to build.







Mortgage Fraud Red Flags Homebuyers Should Check Before Closing

Building a Sustainable Food Supply Chain: Lessons from the Artisan Cheese Industry

Clear HR Policies and Early Intervention are Reshaping Workplace Risk Management

Myths About Dermaplaning That You Should Ignore

How to Rebuild Your Daily Routine After a Serious Injury

How Virtual Crypto Cards Simplify USDT Spending

How To Compare Houston, Texas Neighborhoods Before Buying a Home

Interactive Museums in Miami, Florida: Five Hands-On Attractions Worth Visiting

Why Short Financial Gaps Need Different Solutions

How Admissions Teams Use Viddo AI For Campus Walkthroughs

100 Motivational Quotes to Inspire You in 2026

How to Create a Vision Board That Actually Works (2026)

22 Best Self-Help Books to Read in 2026

How to Achieve Personal Growth in 2026

New Year Wishes and Quotes to Inspire and Celebrate (2026)

Loeb Smith reviews: Why Crypto Licensing Demands Patience, Structure, and Skepticism

Your Guide to Building the Life You Want as a Medical Professional

Romantic Cabins In Tennessee: A Guide to Location, Privacy, And Scenic Views

AI SEO Tools Every Website Owner Should Know

What to Put in Diaper Bag: The Ultimate Checklist for Parents on the Go All the Time
-
 Motivation6 years ago
4 Fun New Hobbies To Try This Year
-

 Quotes4 years ago
53 Motivational Gym Quotes to Fuel Gym Workout
-
 Quotes11 years ago
50 Most Powerful Quotes Ever Spoken
-

 Travel2 years ago
Why You Should Travel More: The Many Benefits of Seeing the World
-
 Quotes11 months ago
100 Motivational Quotes to Inspire You in 2026
-

 Quotes3 years ago
43 Inspirational Quotes About Thoughts
-

 Quotes4 years ago
Motivational Quotes by Famous People
-
 Quotes1 year ago
100 Motivational Quotes to Start Your Day with Positivity